For its new Global Outlook on Sustainability report, Mintel spent three years surveying consumers’ sustainable attitudes and actions across 16 global markets.
Here are the standout findings that cosmetics companies should know.
Reality check: consumers are focused on emissions and resources
Consumers’ growing prioritisation of water shortages as a top three environmental concern (up 8% 2021-3 into third place, behind climate change and air quality, with 35%) reflects how water stress has become a growing reality worldwide.
It is now the world’s fastest-growing concern.
Exposure to extreme weather events and supply line shortages has seen sustainability shift from a “nice to have” premium purchase to an essential issue.
The ascent of water shortages from fifth to third place in consumers’ priorities over the past three years is symptomatic of a population directly impacted by – as opposed to increasingly informed about – climate change.
This marks a new era where environmental issues become pressing issues of self-preservation and a desire to conserve resources for future resilience.
In 2023, water shortages are now more likely to be cited than climate change itself as a top three concern in Mexico, France and Spain, and jointly so in Italy.
When it comes to being the number one concern, water shortages lead in Mexico (26%), Spain (25%) and France (20%) and are tied with climate change itself in Brazil (16%) and Italy (20%).
The UN’s World Water Day conference revealed that global water withdrawal demand will grow by 55% towards 2050, while the World Resources Institute reports that as many as 4 billion people experience water stress conditions.
Rising water concerns have taken place against a backdrop of growing engagement from exposure to the climate crisis happening right outside of people’s windows.
As a result, since 2021, the proportion of consumers who believe that their country is suffering from climate change are now in the majority (at 51%), representing an attitudinal shift of 7 points between 2021 and 2023.
Packaging has peaked as an activation point for consumers
Meanwhile, the less practical, more emotive issue of plastic pollution has slid down consumers’ agendas as they increasingly focus on their personal supply shortages of food and water, and are educated to realise that other issues might be generating more emissions.
Activism has played a role here.
In particular, hit documentary Seaspiracy’s dissemination of Sea Shepherd’s revelation that 46% of plastic in the Great Pacific Garbage Patch was actually fishing nets.
All of this is not to devalue the importance of ocean plastic as a rallying call to action (it has arguably been the posterboy/girl for the past decade’s upwelling of consumer and media engagement), or the enormous problem virgin plastic production – and disposal – presents.
The statistics remain alarming, with 99% of plastics being made from fossil fuels.
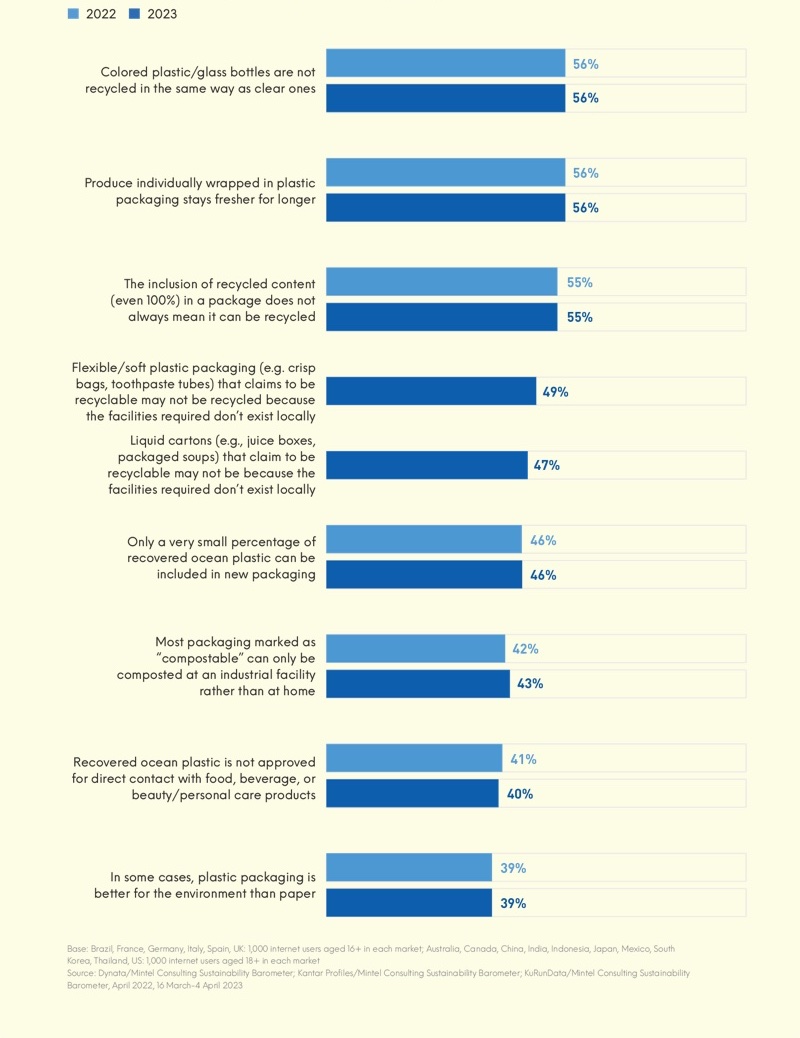
Figure 1: Packaging understanding levels
In packaging, consumers have been corralled – and in some cases shamed – to go plastic free.
One example saw customers who didn’t bring their own bags to Vancouver’s East West Market forced to carry their groceries in plastic bags marked ‘wart ointment wholesale’ or “into the weird adult video emporium”.
On the other hand, a profusion of limited-edition packaging launches using elements of repurposed or recycled ocean plastic have led consumers to believe that anything is possible.
In Mintel’s survey, only 46% say that they know that recovered ocean plastic’s packaging potential is extremely limited and only 43% understand that most packaging marked as ‘compostable’ can only be composted at an industrial facility rather than at home.
Carbon offsetting in crisis
Of particular concern to companies is consumers’ distrust of the very policies at the heart of their drives towards net zero.
It is telling that while 76% of consumers agree that we need to protect more areas so that nature can recover from existing environmental issues, 66% say they would prefer for companies to reduce their own carbon emissions, rather than use carbon offsetting programmes outside of their own area of business.
This highlights a growing disconnect between consumers’ and companies’ goals, and the murky methodologies sometimes employed to achieve them.
Projects preventing deforestation form the basis of most carbon credit programmes used by corporations to assert the carbon neutrality of their businesses or products.
But they need to prove that their forests are intact and the activities are directly preventing deforestation, in order to earn saleable certified emission reduction (CER) credits, each equivalent to one tonne of CO2.
However, investigative journalism by the likes of Propublicca and The Guardian has repeatedly found that even the most verified of ventures are mired and fail to deliver ‘additionality’ (positive impacts that would have not have happened otherwise).
In the wake of such revelations (vehemently challenged by carbon standard Verra), it’s understandable that the public is challenging companies to become more involved and invested in their conservation and sequestration projects.
Activists making consumers more savvy
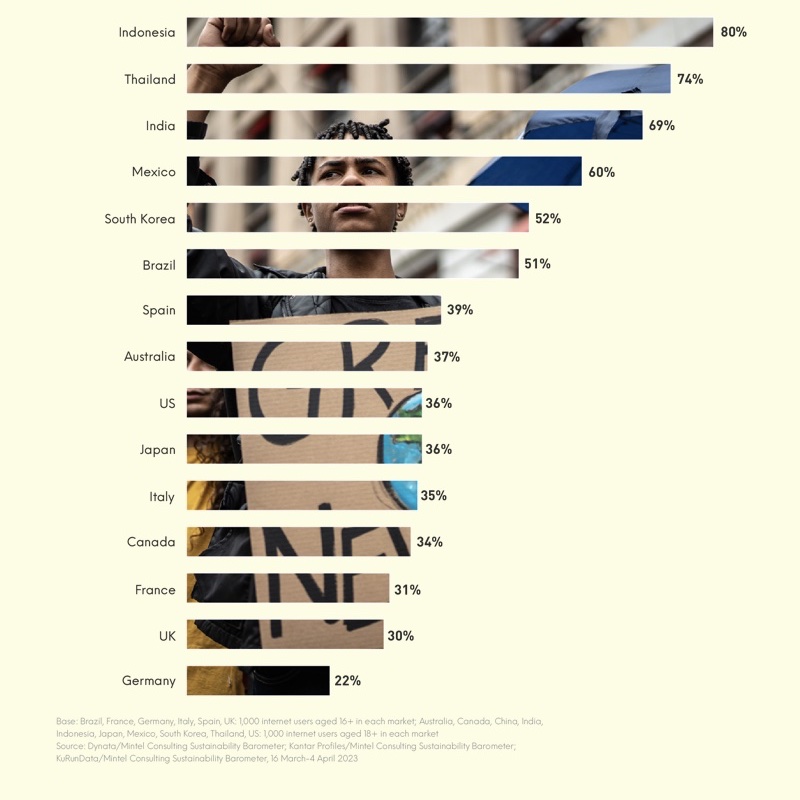
Mintel’s research shows that 47% of consumers perceive activists as legitimate protestors while 46% say they’ve raised their awareness of environmental issues.
Activists are also becoming instrumental in holding brands to account for greenwashing, exemplified in the case of Innocent drinks in the UK.
Its Little Drinks, Big Dreams advert was banned by the Advertising Standards Authority (ASA) after Plastics Rebellion occupied its headquarters and reported it for claiming that drinking its smoothies was good for the environment.
Figure 2: Consumers saying 'eco-activism has raised my awareness of environmental issues'
The clear inference is that, as ‘environmentally friendly’ disappears down the credibility plughole, a new, more honest marketing lexicon around ‘less’, ‘reduced’ and ‘more efficient’ will prove increasingly resonant with resource-conscious customers.
When canvassed on what would encourage them to consider buying more responsible products, top of the list (for 41% of consumers) is the convenience of a Nutriscore-style colour-coded impact labelling system on pack.


